
Your crew is halfway through an exterior repaint when the wind shifts. A fine mist travels beyond the work area and settles on nearby vehicles.
Across town, another painting contractor receives a call from a property manager. Tenants report strong odors after an interior coating project. Meanwhile, a residential crew discovers several layers of old paint beneath a peeling finish.
Each situation begins with ordinary painting work. Each also raises questions about property damage, health, cleanup, and insurance.
Pollution risks for Florida painters can arise from the products crews apply, the surfaces they disturb, and the waste they leave behind. A general liability certificate alone does not explain how those exposures are insured.
The solution starts before the crew arrives. You need an accurate description of the work, a practical site plan, and insurance that has been reviewed against your actual operations.
This guide explains the main exposures, the coverage questions worth asking, and the controls you can build into estimating and project management.
Examples are hypothetical. This article provides general education, not a project-specific safety plan or coverage determination. Applicable requirements and policy wording control.
Understanding Pollution Risks for Florida Painters
Most painting contractors recognize overspray as a potential property damage problem. However, pollution-related allegations can involve much more than visible paint spots.
Think about three parts of every job:
- What you bring: Coatings, primers, solvents, cleaners, and equipment fluids.
- What you disturb: Existing paint, dust, debris, and underlying materials.
- What you remove: Leftover products, contaminated coverings, wash water, and waste.
Next, consider where those materials could travel. Air movement can carry particles beyond a work area. Occupants may enter spaces before the project team expects them. Rain can reach unsecured debris or waste containers.
This approach gives you a useful starting point for a walkthrough. Ask where a material could go, who could encounter it, and who is responsible for keeping it contained.
Florida projects require site-specific planning
An occupied Tampa office, a coastal condominium, and an older Jacksonville home present different conditions.
For example, a condominium project may involve balconies, shared walkways, nearby cars, and residents entering throughout the day. A historic home may require a detailed review of existing coatings before preparation begins.
Describe those conditions in the estimate. Do not reduce the entire risk discussion to the number of square feet being painted.
Separate hazards from insurance definitions
A material can require careful handling even when its treatment under an insurance policy is uncertain.
Likewise, calling a product “water-based” or an incident “just overspray” does not decide coverage. The insurer must evaluate the allegations, policy definitions, exclusions, endorsements, and applicable law.
Keep prevention and insurance review connected. Neither one should wait for the other to solve the entire problem.
Paint Overspray: A Small Drift Can Affect Many Properties
Imagine your crew spraying a commercial exterior beside a parking area. Several vehicles remain nearby because their owners did not receive the relocation notice.
Later, drivers report paint deposits on windshields and body panels. A neighboring tenant also reports residue on storefront glass.
The immediate problem involves more than cleaning. You need to identify affected property, preserve evidence, coordinate inspection, and avoid causing further damage during removal.
Inspect beyond the building you are painting
Before spraying, walk the surrounding area with the crew leader. Look for:
- Parked vehicles and active parking entrances.
- Boats, pools, outdoor furniture, and neighboring buildings.
- Open windows, balconies, doors, and air intakes.
- Pedestrian routes and outdoor dining areas.
- Sensitive equipment or surfaces near the work zone.
Then agree on protection, access restrictions, and communication with the customer.
A parking notice is useful only if someone verifies that the area is clear. Assign that responsibility before work starts.
Give supervisors clear stop-work authority
Your plan should identify conditions that require a pause. Examples include failing containment, changing wind conditions, unexpected foot traffic, or an occupied area that cannot be protected.
Set project-specific operating limits using the product and equipment instructions, site conditions, and qualified safety guidance. Avoid treating one generic wind-speed number as suitable for every application.
Also decide who can authorize a different method. Switching from spraying to rolling may change labor time and pricing. Resolve that possibility in the proposal instead of forcing the crew to improvise.
Do not promise that every overspray claim is insured
When reviewing coverage, describe the exact scenario. Paint on a neighboring car may raise different issues from allegations that airborne material caused illness or contaminated an occupied space.
Ask your agent to review both general liability and pollution coverage. If an incident occurs, report the facts through the appropriate channels rather than deciding on your own that only one policy could apply.
Paint Fumes and Indoor Air Complaints
Interior projects need an occupancy plan as well as a production schedule.
Consider a hypothetical office repaint performed overnight. The customer expects employees to return at 8 a.m. Your crew assumes that the building manager will arrange ventilation. The manager assumes your painters will handle it.
By morning, neither party has confirmed that the space is ready for use.
That gap in responsibility is preventable. Before starting, identify who will coordinate ventilation, communicate with occupants, and authorize reentry.
Low-VOC does not mean hazard-free
EPA explains that some products labeled “low VOC” or “no VOC” under outdoor-air rules can still contain volatile chemicals of concern indoors. The label alone is not a complete assessment of indoor exposure.
Choose products carefully, but also review how they will be used. Obtain the current safety data sheet, product instructions, and any application or ventilation requirements.
A customer requesting a low-odor product still needs a clear schedule and occupancy plan.
Plan where air will move
EPA identifies paints and related remodeling products as potential indoor pollutant sources and emphasizes source control and ventilation.
For a contractor, the practical question is whether the ventilation plan fits the building and task. Simply adding a fan may move contaminants toward another occupied area.
Coordinate with the building representative and qualified personnel where needed. Review air intakes, shared systems, adjacent spaces, and exhaust locations. Do not alter building systems without authorization and an appropriate plan.
Also distinguish “dry to the touch” from the conditions needed for safe occupancy. Follow the product guidance and project-specific assessment instead of promising a universal waiting period.
Take complaints seriously and document facts
If an occupant reports symptoms, stop the affected operation and address immediate safety needs. Seek emergency assistance when warranted.
Record the product used, application method, work location, timing, ventilation arrangements, and the person who reported the concern. Preserve the safety data sheet and batch information if available.
Avoid diagnosing the person or assuring them that a smell cannot be harmful. Qualified responders can evaluate health and exposure concerns.
Lead Paint: The Risk May Begin During Preparation
You do not need to sell lead-abatement services to encounter lead-related risks.
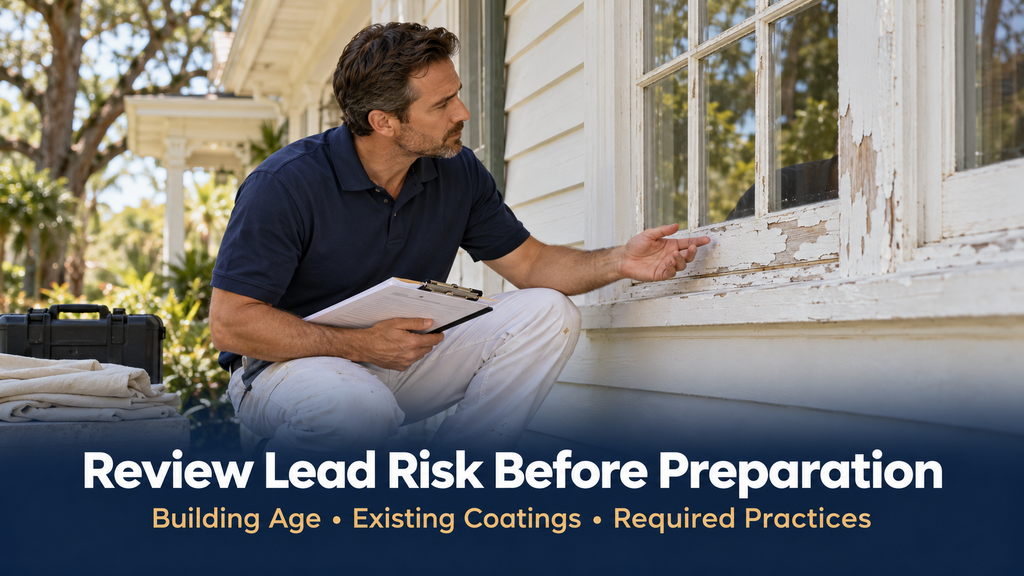
Scraping, sanding, or removing old painted components can create dust and debris before the first coat of new paint is applied. Florida’s Department of Health identifies renovation of pre-1978 housing and child-occupied facilities as an important lead-safety concern.
Make building age and existing-coating questions part of estimating. A vague answer such as “the house was remodeled years ago” should prompt follow-up rather than an assumption about underlying layers.
When does the EPA RRP Rule apply?
EPA’s Renovation, Repair and Painting Rule generally covers paid work that disturbs paint in pre-1978 housing and child-occupied facilities. Painting preparation can qualify. Covered firms need firm certification, including sole proprietorships. The rule has specific exceptions, so scope and building use matter.
This does not mean every commercial building falls under RRP. However, a commercial property can contain a qualifying child-occupied facility. Determine the actual use instead of relying only on its zoning or lease description.
Firm certification and renovator training are separate
A business certificate and an individual’s training credential serve different purposes.
EPA requires covered firms to be certified. Covered work also requires a certified renovator, with other participating workers either certified themselves or trained on the job by a certified renovator.
Before scheduling a covered project, confirm the firm’s status, the assigned renovator, and the crew’s training. Keep renewal dates in your scheduling system.
A crew should not arrive expecting to complete required training after preparation has already begun.
Do not guess whether the paint contains lead
EPA does not require testing before every RRP project. However, absent qualifying documentation that affected paint is not lead-based, otherwise covered work must follow the rule. Testing used for an RRP determination must follow accepted methods and be performed by appropriately qualified people.
Ask for relevant reports during estimating. Check that the information addresses the surfaces your crew will disturb.
A test of one component should not become an unsupported conclusion about the entire property.
Small Jobs Still Need a Lead-Safety Review
The RRP minor repair and maintenance exception generally involves disturbing no more than six square feet of interior paint per room or 20 square feet on the exterior. Interior work in the same room is aggregated over a 30-day period. Exterior limits apply to the total, not separately to each wall.
Window replacement, demolition of painted surfaces, and prohibited practices do not qualify for that exception.
Treat these limits as a rule to evaluate carefully, not a shortcut for avoiding containment.
For example, an estimate may begin with several small patches. Once scraping starts, deteriorated paint may extend beyond the original repair areas.
Build a scope-change procedure for that situation. The crew should pause, document the condition, and obtain a compliant revised plan before expanding the work.
Required practices go beyond laying down a tarp
For covered work, EPA describes requirements involving pre-renovation education, containment, worker training, cleaning, verification, and records. Certain methods are prohibited or restricted. Required job records generally must be retained for three years. Additional requirements may apply to HUD-assisted housing.
Use the current EPA guidance and qualified training to establish the full procedure. A short blog checklist cannot substitute for that training.
In your office, create a project folder that holds the required documents from start to finish. Give one person responsibility for confirming that the file is complete.
Renovation certification is not abatement certification
Lead abatement is a separate regulated activity. EPA’s lead-based paint activities program addresses services such as inspections, risk assessments, and abatement, with separate training and certification requirements.
If a customer asks your company to permanently eliminate lead hazards, clarify the scope before accepting the job. Do not assume your RRP credentials authorize every lead-related service.
That scope clarification also belongs in your insurance review. Tell the agent whether you perform ordinary renovation, encounter existing lead incidentally, or undertake intentional lead-related work.
OSHA Worker Protection Requires Its Own Review
RRP compliance and worker exposure protection involve different requirements.
OSHA’s construction lead standard applies to construction work where employees may be exposed to lead. It addresses exposure assessment, controls, protective measures, training, and other obligations. Certain tasks require interim protections while the employer evaluates exposure. Its application is not limited to pre-1978 housing.
Therefore, a conclusion that RRP does not apply does not settle your OSHA responsibilities.
Have a qualified safety professional evaluate the tasks and materials. This is particularly important when crews move into unfamiliar preparation methods or specialty coatings.
A respirator needs a program behind it
When respirators are required, OSHA generally requires a written respiratory protection program, appropriate selection, medical evaluation before use, and training. Tight-fitting respirators require fit testing before initial use and at least annually, among other triggers.
A particulate filter does not provide the same protection as a cartridge selected for a particular vapor hazard. Selection must match the exposure and applicable requirements.
Make equipment availability part of planning, but do not stop there. Confirm that workers have the required training, evaluations, and fit testing for the equipment they will actually use.
Employee exposure concerns should also be reported through your workers’ compensation and incident procedures as appropriate. Pollution liability coverage should not be treated as a replacement for workers’ compensation.
Wash Water, Solvents, and Waste Can Extend the Exposure
The application phase may be finished while the environmental work is still incomplete.
Ask your crew leader a simple question: Where will every leftover material go?
The answer should address unused product, paint chips, contaminated coverings, cleaning liquids, and collected wash water.
Keep material out of stormwater
Stormwater can carry pollutants from paved areas into drainage systems and receiving waters. EPA’s stormwater guidance addresses controlling the release of paints, solvents, debris, and related wash water.
Before pressure washing or cleanup, identify nearby drains and water features. Plan collection and containment before the work begins.
Do not rinse paint waste into a street or storm drain. For any proposed sanitary-sewer disposal, confirm acceptance and applicable local requirements first. A water-based product label does not establish disposal permission.
During rain delays, check waste containers and protective coverings. The job should remain controlled when the crew is away.
Confirm the correct waste route
Florida DEP’s hazardous waste requirements depend on the waste and the generator’s status. Some painting-related waste may require hazardous waste management; not every paint waste has the same classification.
Ask your waste provider or environmental adviser to help determine the proper route. Confirm that the receiving facility accepts the specific business waste you generate.
Do not assume a residential household collection program accepts commercial material.
Keep disposal receipts and any required shipping records with the job or waste-management file. Those records help show where the material went and who handled it.
Does General Liability Cover Painting Pollution Claims?
General liability may leave significant gaps for pollution-related claims. The answer depends on the complete policy and the facts.
Construction GL policies may contain a pollution exclusion along with endorsements that broaden it. A total pollution exclusion can remove exceptions present in the base form. Other endorsements may address specific substances or operations.
This is why a certificate showing a large liability limit is not enough for an environmental review.
Ask your agent to identify the relevant forms and discuss examples involving your business:
| Situation | Coverage question to raise |
|---|---|
| Paint deposits on neighboring vehicles | How do GL and pollution forms address this alleged damage? |
| Occupants report illness after coating work | What wording applies to fumes and indoor releases? |
| Preparation spreads lead dust | Are lead and the particular operation covered or excluded? |
| Wash water reaches a drainage system | How are cleanup costs and third-party allegations treated? |
| A complaint arrives after completion | Which timing and completed operations provisions apply? |
These are review questions, not predicted claim outcomes. Ask for answers tied to policy language.
Contractors Pollution Liability Insurance for Painters
Contractors pollution liability, often called CPL, is designed to address specified pollution exposures arising from covered contracting operations. Available coverage can include third-party bodily injury, property damage, and pollution cleanup costs. Terms vary by insurer and form.
Buying CPL is a useful conversation, but the policy still needs to fit your work.
Describe operations completely
Prepare a short business profile before requesting proposals. Include:
- Residential, commercial, and industrial work percentages.
- Interior and exterior application methods.
- Surface preparation and paint-removal methods.
- Specialty coatings, solvents, and cleaners.
- Work involving older buildings or known lead.
- Subcontracted tasks, transport, and waste handling.
Add one or two sample contracts and representative project photos.
Avoid describing the company only as “a painter.” That label does not tell an underwriter whether you roll interior walls, spray occupied complexes, or remove industrial coatings.
Check lead and overspray explicitly
Ask whether the proposed form addresses lead, airborne paint, indoor releases, and the methods your crews use. Identify any excluded substances or restricted operations.
Also distinguish incidental disturbance from intentional remediation. Do not assume that a pollution policy automatically authorizes or covers lead abatement.
If the proposal relies on an endorsement to provide needed coverage, obtain and review it before binding.
Review timing and completed work
CPL is available with different coverage triggers, including claims-made-and-reported and occurrence forms. Some products also offer completed operations, transportation, disposal-site, and emergency-response features. These are features to verify, not universal promises.
Ask your agent to explain when a claim must arise and be reported under the proposed form. For claims-made coverage, review the retroactive date and options when changing or ending coverage.
For occurrence coverage, review how the form determines the relevant event and timing. Do not assume it uses exactly the same wording as your GL policy.
Understand what you may have to pay
Request a practical explanation of the deductible or retention, defense expenses, limits, and any sublimits.
Also ask how the policy treats emergency cleanup, consent to expenses, damage to your own property, and regulatory proceedings. Never assume that fines, penalties, or every cleanup expense are insured.
An umbrella or excess policy needs its own review. Ask whether it applies above the pollution policy and whether it contains exclusions that affect the intended protection.
Subcontractors and Contracts Can Change the Risk
Hiring another company does not remove the need to manage the project.
Travelers recommends evaluating subcontractor qualifications, using appropriate contracts, overseeing work, and retaining documentation when managing construction pollution exposures.
For painting operations, make the review specific to the assigned task. A subcontractor qualified for routine repainting may not be qualified for lead-related preparation or specialized removal work.
Before work begins, confirm who controls containment, ventilation, waste removal, and incident reporting.
Then review the subcontractor’s relevant coverage with your agent. A GL certificate by itself does not establish pollution coverage or confirm that the assigned operation is insured.
Article; Hiring Painting Subcontractors in Florida: Insurance Checks Before Work Begins will examine subcontractor insurance verification in more detail.
A Practical Pollution Prevention Plan for Every Job
The best procedure is one your estimator, supervisor, and crew can use consistently.
Build the plan around five decisions.
1. Screen the property before quoting
Record the building’s age, use, occupancy, neighboring exposures, and drainage features. Ask for available coating or environmental reports.
Flag any uncertainty that could change the preparation method or compliance requirements. Price the work after resolving material assumptions.
2. Match the method to the site
Choose the product and application method with the surroundings in mind. Include time for containment, ventilation arrangements, waste handling, and cleanup.
If the customer’s schedule conflicts with those needs, resolve the conflict before accepting the job.
3. Assign responsibility by name
Identify who checks surrounding property, coordinates occupants, monitors site conditions, and authorizes a pause.
A plan that says “the crew will handle it” leaves too much room for misunderstanding.
4. Record changes during the work
Document product substitutions, expanded preparation, unexpected occupants, and changes in weather or containment.
When conditions materially change, reassess the plan. A signed estimate should not force the crew to continue with a method that no longer fits the site.
5. Close out the project deliberately
Confirm cleanup, waste removal, required verification, and communication with the customer. Save the records before moving the crew to the next project.
Review near misses at the next team meeting. A minor containment failure can reveal a process problem before a larger loss occurs.
What to Do After an Overspray or Pollution Incident
Prepare a short response sheet that supervisors can find quickly. Include emergency contacts, insurer reporting instructions, and the office person responsible for coordination.
If an incident occurs:
- Stop the affected task when safe. Prevent additional release or exposure without placing workers at risk.
- Protect people first. Restrict access and seek emergency assistance when necessary.
- Notify the responsible contacts. Inform the supervisor and property representative promptly.
- Report to insurers as required. Follow policy instructions and involve all potentially relevant coverage lines.
- Preserve the facts. Record timing, materials, locations, witnesses, photos, and actions taken.
- Arrange qualified response. Coordinate specialized cleanup and inspections, including insurer consent where required.
- Address regulatory reporting. Determine applicable reporting duties promptly with qualified assistance; do not wait for a coverage decision.
Do not attempt an unfamiliar cleanup just to make the complaint disappear. Improper removal can spread contamination or damage property further.
Keep communications factual. You can acknowledge a concern and explain the response without promising payment or speculating about medical outcomes.
Protect Your Business Before the Paint Starts Moving
Pollution risks for Florida painters belong in estimating, crew planning, and insurance reviews.
Start with the property and the work. Identify what your team will apply, disturb, and remove. Then decide how to control those materials and document the process.
Finally, review the coverage using realistic examples. Ask how the policies address overspray, fumes, lead, cleanup, and work completed months earlier.
Before your next project, bring one typical job and one challenging job to your insurance adviser. Review the products, preparation methods, occupancy plan, subcontractors, and waste arrangements together.
A clear plan gives your crew better direction. It also gives your business a stronger foundation when a customer, property manager, or insurer asks what happened.
Frequently Asked Questions
No single label decides coverage. The material, alleged damage, policy wording, and circumstances all matter. Ask the agent to evaluate both visible property damage and any contamination or injury allegations.
No. Product selection is only one part of the review. Application, exposure, overspray, cleanup, and disposal still need planning.
No. Where the RRP Rule applies, firm certification and the required individual training serve separate roles. Verify both before accepting covered work.
No. Abatement and related lead-based paint activities have separate requirements. Confirm qualifications and coverage for the precise scope being offered.
Review exposure rather than company size alone. A small crew working in an occupied property or near sensitive neighboring property can still encounter significant allegations. Compare the actual work against the proposed coverage.